

B9: Cash Advance analysis by Appwee
When money is tight between paydays, I understand why an app such as B9: Cash Advance can look appealing. I tested it as a finance app from B9 - Get Your Paycheck Early, and my first impression was that it is built around one focused task: helping an eligible user access part of an expected paycheck before the normal payday arrives. That narrow purpose is also its main strength. It is easier to understand than a full budgeting suite, but it is not a replacement for a proper emergency fund or a long-term plan.
The app is free to install and is rated for Everyone, which makes it approachable on a household phone. Still, “Everyone” should not be confused with “suitable for every person in the household.” A paycheck advance is a financial decision, so the person using it needs to understand repayment timing, account ownership, and the effect of taking money early. My overall view is positive for someone dealing with a short, temporary gap, but I would be careful about treating it as spare income.
How B9 fits into a shared household
A realistic example is a household where one person handles rent and another covers groceries or transport. A bill may arrive before the next payroll deposit, while the household’s money is technically on the way. In that situation, B9 can be useful because it focuses on bringing forward access to earned pay rather than asking the user to apply for a traditional personal loan. The practical benefit is speed and simplicity, provided the user is eligible and comfortable with the resulting repayment arrangement.
I would keep the app on the phone of the person whose paycheck is involved. That sounds obvious, but shared devices can blur financial boundaries. A partner, parent, or roommate should not casually open a finance app and assume that the available amount belongs to the whole household. The advance is connected to one user’s financial situation, not to a shared pool of money.
That distinction matters when several people use the same Android or iOS device. The app itself is not a household budgeting board, and I would not use it as a way to coordinate everyone’s spending. Instead, I would treat it as a private tool for one account holder, then discuss the household consequence separately. If an advance is used for groceries, for example, the household should know that the next paycheck may have less flexibility.
My most useful habit with an app like this is to decide the purpose before opening it. “Cover this week’s medicine,” “avoid a late utility payment,” and “bridge a delayed work expense” are understandable purposes. “I have some money available, so I may as well take it” is a warning sign. That small pause keeps the app from turning an occasional bridge into a recurring part of the household budget.
Keeping the account boundary clear
During setup, I would use the worker’s own identity, income information, and financial connections rather than trying to build a shared login. The right boundary is simple: one person, one account, one clear understanding of where the advance goes and how it will be settled. A shared phone does not justify shared credentials.
This is especially important when a household has separate incomes. If one person takes an advance to cover a joint expense, both people should agree whether it is a temporary contribution, a reimbursement, or simply that person’s responsibility. Without that conversation, a convenient advance can create confusion later. The app may solve the timing problem while leaving the relationship problem untouched.
I also recommend checking every screen during setup instead of tapping through quickly. Pay attention to the amount being requested, the expected timing, and any terms shown before confirming. Financial apps deserve slower reading than social apps. If the wording is unclear, I would stop and resolve that question before proceeding rather than relying on an assumption.
Another sensible boundary is device access. Use the phone’s normal lock and keep the app away from casual browsing by children or guests. I would not save screenshots of sensitive account information in a shared photo library, and I would avoid discussing the available advance as though it were guaranteed household cash. These are ordinary privacy habits, but they matter more when a device moves between family members.
The current version is 3.70.0, and the app requires Android 8.0 or later. That makes compatibility worth checking before planning around it, particularly if a household keeps an older spare phone. An outdated device can create its own friction through slow screens, security limitations, or an inability to install the current release. I would confirm that the intended phone can run the app before making it part of a payday plan.
Coordinating the advance with real bills
B9 works best when the user connects the advance to a specific date and obligation. I would write down the bill, the amount needed, and the next paycheck’s existing commitments before requesting anything. This prevents a common mistake: solving today’s shortage while quietly creating a larger shortage when regular pay arrives.
For a shared household, a short conversation can be enough. The account holder might say, “I am using an advance for the electricity bill, so I will have less room for discretionary spending after payday.” That is more useful than announcing only that the bill has been paid. It gives the household a chance to adjust meals, transport, or optional purchases before the next deposit.
I would also avoid stacking several small decisions without a running note. An advance can feel less serious when viewed one transaction at a time, yet the household experiences the combined effect. A basic phone note with the purpose, expected settlement, and remaining payday obligations is a surprisingly effective safeguard. It is not a feature I would assume the app provides; it is a workflow I would use alongside it.
Timing is another reason not to wait until the last possible moment. If a payment is due today, an advance app should not be treated like an instant guarantee. Eligibility, account review, bank processing, and the user’s own circumstances can affect what happens. I would use B9 as part of a plan made before the deadline, not as the only rescue option after a payment has already failed.
This is where the app differs from a conventional budget tracker. A budget tracker helps explain where money goes and can support longer-term planning. B9 addresses access to pay before the normal payday. Those tools can complement each other, but they solve different problems. If the household’s recurring issue is overspending, a budget is the better first step. If the issue is a one-off timing mismatch, an advance may be more relevant.
Age, trust, and responsible use
The Everyone rating tells me the app is presented for a broad audience, but financial responsibility still belongs with the adult account holder. I would not let a child or teenager operate the account simply because the app appears in an app store with a general age label. A young person may understand how to navigate screens without understanding paycheck deductions, recurring expenses, or the consequences of relying on early access.
In a family, trust should work in both directions. The person requesting an advance should know why it is needed, while other household members should respect that the account contains private financial information. I would not ask a partner to hand over a password as proof of honesty, and I would not use a shared device as permission to inspect the account. A clear verbal agreement about the purpose and repayment effect is healthier than informal surveillance.
Older relatives may need a different kind of help. If someone is unfamiliar with cash advance services, I would sit beside them and explain each step without taking control of the account. Read the amount, the timing, and the confirmation together. Let the account holder make the final decision. This approach reduces the risk of a well-meaning family member requesting money on someone else’s behalf without understanding the consequences.
Trust also means being honest about whether the problem is temporary. If the user is short every pay cycle, B9 may provide repeated relief without fixing the underlying gap. In that case, I would look at recurring bills, subscription costs, transport expenses, and income timing before making another request. The app can be useful in an emergency, but regular dependence is a signal to seek a broader solution.
Where the app feels strong and where it needs caution
B9’s clearest advantage is focus. The store summary describes advancing money from a paycheck before payday, and that is exactly the use case I would keep in mind. The interface concept is easier to grasp than a bank app filled with unrelated tools. For a worker who needs a short bridge and already understands the effect on the next paycheck, that directness can be valuable.
Its public reception is also encouraging: the app holds a 4.6 average from around 18 thousand ratings, with more than 7 thousand written reviews and over 1 million installs. Those figures suggest that many people have found the service relevant enough to try and rate. They do not guarantee that every user will receive the same result, so I would still read the live terms and eligibility details carefully.
The main weakness is built into the concept. Getting money early does not create additional income. It changes the timing of access, which can make the following payday feel smaller or more constrained. Someone already balancing several overdue bills may need debt advice, employer support, a bank conversation, or a revised budget rather than another advance.
I would also compare the app with alternatives before relying on it. An employer’s own wage-access option may fit better if it is available and its terms are clearer. A traditional savings buffer is usually healthier for a predictable expense because it does not reduce a future paycheck. A bank overdraft or credit product may offer a different structure, but it can also carry costs and risks of its own. The best choice depends on the exact terms, not on the label attached to the product.
One non-obvious trade-off is convenience versus attention. Because the app is designed around a quick financial need, it may encourage a user to focus on “can I access money?” instead of “what happens after I access it?” I would deliberately reverse those questions. First map the next paycheck, then decide whether early access genuinely improves the situation. That simple order of operations makes the tool safer to use.
Another is household visibility. A private account protects personal information, but secrecy about a joint bill can damage coordination. I would keep login details private while still telling affected household members about the budget impact. Privacy and transparency are not opposites here: the account can remain personal while the consequence of the decision is shared openly.
My household verdict
After looking at B9 through a shared-device and family-use lens, I see it as a practical short-term finance tool rather than a household money manager. I would recommend it to an eligible worker who has a specific, temporary gap, understands the next-payday effect, and can keep the account separate from other users of the phone.
I would skip it if the household needs help controlling monthly spending, if the user cannot explain how the advance will be settled, or if every payday already depends on taking money early. In those cases, a budget review, an emergency savings plan, or a conversation with an employer or financial counselor is likely to be more useful. The app should support a plan, not become the plan.
For someone considering installation, my practical checklist is short: use the correct personal account, review the confirmation screens, identify the exact bill, tell anyone affected by the smaller future balance, and keep the device protected. I would also check that the phone meets the Android requirement and that the current terms suit the situation before committing to a request.
My final recommendation is cautious but favorable: B9 can be a sensible bridge when timing is the problem and the user has a clear repayment picture. Its free access and focused design make it easy to consider, while its 4.6 average and broad adoption show that it has attracted substantial user interest. Just remember what it is offering: earlier access to expected pay, not extra money. Used with firm account boundaries and honest household coordination, that distinction keeps the app useful instead of letting it quietly become a financial habit.
Gallery
B9: Cash Advance Pros and Cons
- Fast access to small cash advances when eligible
- No traditional credit check is required for many users
- Transparent repayment date shown before accepting an advance
- Automatic repayment can simplify managing the balance
- Useful budgeting tools help track income and upcoming bills
- Advance limits may start low and increase slowly
- Eligibility depends on account activity and recurring income
- Optional fees may apply for instant transfers or expedited service
- Repayment is typically due on the next payday
- Late repayment could affect future access to advances
B9: Cash Advance Frequently Asked Questions
What is B9: Cash Advance?
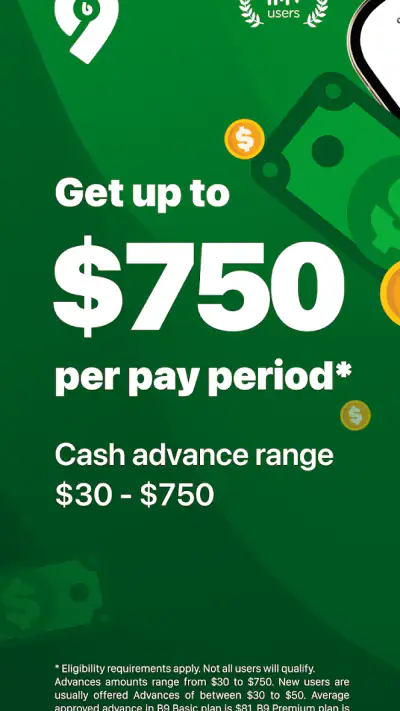
B9: Cash Advance is a financial app designed to help eligible users access part of their expected income before payday. Depending on your account, employer, direct-deposit setup, and other eligibility requirements, the app may offer cash advances, early access to wages, budgeting tools, and related banking features. Availability, limits, and fees can vary, so review the terms shown in the app before accepting an advance.
How much money can I borrow with B9: Cash Advance?
The amount available through B9: Cash Advance is not necessarily the same for every user. Your limit may depend on factors such as verified income, direct-deposit history, account activity, repayment behavior, and information provided during registration. The app should display your available amount and repayment date before confirmation. Do not assume that a previous limit will remain unchanged, because offers can be adjusted over time.
Does B9: Cash Advance charge fees or interest?
B9 may use a membership-based pricing model and can offer different delivery options or features depending on your plan and account status. The total cost of using an advance may therefore differ from one user to another. Before proceeding, carefully check the current membership price, optional expedited-transfer charges, repayment details, and any other disclosed costs. Avoid accepting an offer until you understand exactly what will be withdrawn and when.
How do repayments work in B9: Cash Advance?
Repayment is generally scheduled according to the terms presented when you request the advance, often using a linked bank account or incoming direct deposit. Make sure the repayment account has enough funds on the scheduled date to reduce the risk of a failed payment or account problems. If your income date changes, contact B9 support promptly and review the app’s repayment information rather than assuming the date will update automatically.
Is B9: Cash Advance safe and available to everyone?
B9 uses account verification and financial information to determine eligibility, so users should provide accurate details and download the app only from an official store or verified source. The service is not necessarily available in every country, state, or employment situation, and approval is not guaranteed. Before signing up, review privacy permissions, eligibility rules, membership terms, and customer-support options to decide whether the service fits your financial needs.














